
BILL Spend & Expense (Divvy)
- Rating
- 4.5
- Downloads
- 100.00K
- Content Rating
- Everyone
BILL Spend & Expense (Divvy) - Screenshots
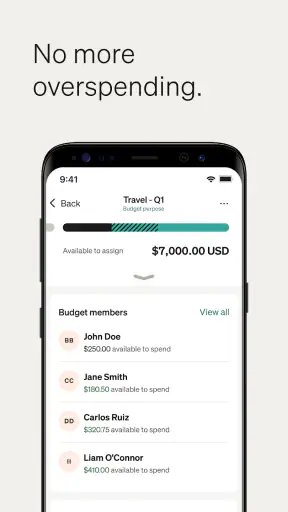
Pros
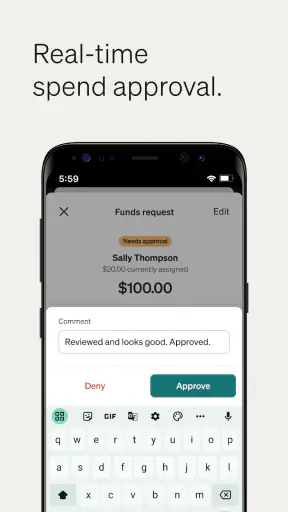
- Real-time card controls help prevent unauthorized or unnecessary spending.
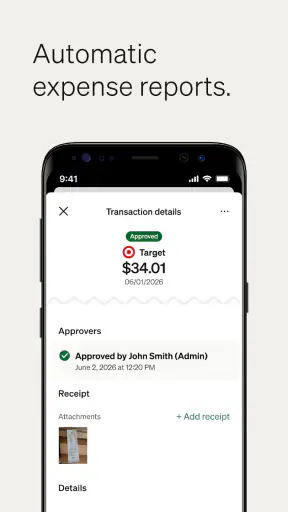
- Built-in receipt capture keeps transaction documentation organized.
- Custom spending limits make it easier to manage employee budgets.
- Automated expense reports can reduce manual finance administration.
- Useful visibility into team spending for managers and finance teams.
Cons
- Approval workflows may feel complicated for small teams.
- Some advanced features may require a paid business plan.
- Employees depend on company setup for access to key functions.
- Limited value for individuals without a business expense account.
- Sync or notification delays can occasionally affect expense tracking.
BILL Spend & Expense (Divvy) - Description
- App Name
- BILL Spend & Expense (Divvy)
- Package Name
- com.divvypay.Divvy
- Developer
- Bill.com Inc.
- Category
- Business
- Last Updated
- Aug 10, 2017
- Version
- 4.0.17
I look at BILL Spend & Expense as a practical business app for teams that need more control over company card spending and employee expenses without turning every purchase into a paperwork exercise. It is developed by Bill.com Inc., and its focus is clear: bring corporate cards and expense management into one mobile workflow. After using it, I found the strongest appeal is not flashy presentation but the way it encourages employees, managers, and finance staff to follow the same process.
The app is free to download and carries an Everyone content rating, which makes it easy to consider for a mixed workplace. It has built a solid audience on mobile, with more than 100 thousand installs and an average score of 4.5 from around 4.3 thousand ratings. Those figures suggest that it is not an experimental side project, although I would still judge it by how well its workflow matches the way your company handles approvals and spending.
How BILL Spend & Expense feels today
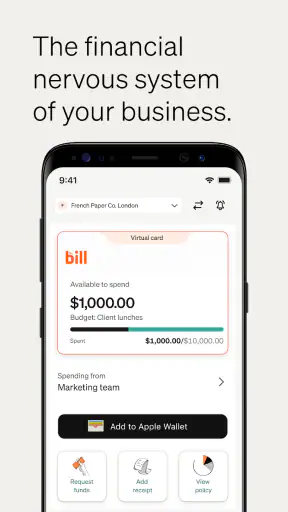
A mobile control center for company spending
The most useful way to understand the app is as a companion to a company spending program rather than as a general personal finance tracker. I would not install it to monitor household groceries or split a restaurant bill with friends. Its value appears when a business gives people access to corporate cards or reimbursable spending and needs a consistent record of what happened afterward.
That distinction matters because business expenses are rarely just about the amount. A finance team may need to know who made the purchase, which project it belongs to, whether it was approved, and whether supporting information was attached. A good mobile experience reduces the delay between paying and documenting. In my experience, that is where this kind of app earns its place: it makes the responsible action available at the moment the transaction is still fresh in the user’s mind.
The interface is best approached as a workflow. Employees can use it to stay aware of their spending activity, while managers and finance users benefit from having information organized around company controls rather than scattered across email, paper receipts, and separate spreadsheets. The exact experience will depend on how an organization configures its account, but the central idea remains useful: corporate spending should be visible before it becomes a month-end surprise.
Where it fits in a normal workday
Imagine a project manager buying equipment for a client visit. With a traditional process, the receipt might stay in a wallet for several weeks, then be photographed at the end of the month while the employee tries to remember the business purpose. A mobile expense tool gives that person a better moment to act: immediately after the purchase, while the receipt and context are still available.
I also see a second everyday use case for distributed teams. An employee working away from the main office may not have access to a desktop finance system when a purchase happens. A phone-based workflow can keep the record moving without waiting for a return to the office. That does not eliminate the need for company policy, but it can remove a common excuse for late or incomplete submissions.
For managers, the benefit is less about entering every detail themselves and more about reviewing information in a consistent format. If a team uses the app properly, approval conversations can focus on whether a purchase makes sense instead of first reconstructing what the purchase was.
The practical difference from ordinary alternatives
The usual alternatives are a shared spreadsheet, email-based receipt collection, a bank statement reviewed at the end of the month, or a separate card app combined with accounting software. Each can work, especially for a very small business with simple spending. The weakness is that these tools divide the process. One place shows the transaction, another stores the receipt, and a third may contain the approval record.
BILL Spend & Expense is more appealing when the company wants those actions to belong to one spending environment. That can reduce manual copying and make accountability easier to follow. It is not automatically better than a full accounting platform, though. A small business with only one cardholder may find a spreadsheet faster, while a larger finance department with complex reporting may need a broader system around this app.
The important trade-off is convenience versus configuration. The more a company relies on approval rules and spending controls, the more time it may need to spend setting up a process that employees understand. An app can centralize information, but it cannot decide whether your policy is clear or whether managers review requests promptly.
What the current version tells me
The current version is 4.0.17, and that version number gives the product a more mature feel than a first-generation mobile companion. I would treat it as an established tool that has evolved beyond a simple receipt camera, while still separating that observation from assumptions about future releases. A version number alone does not prove that every workflow is perfect, but it does indicate that the mobile product has had room to develop.
The app was released on August 10, 2017, so it has had a long period to become part of business routines. That history is useful for companies that dislike adopting tools that may disappear quickly. At the same time, older products often carry accumulated complexity. New users may encounter terminology or screens designed around an organization’s internal setup rather than a simple consumer-style experience.
Changes and product evolution in context
From the current product identity, the evolution is easy to see in the combination of corporate cards and expense management. The app is not presenting card activity as an isolated banking feature. It is trying to connect spending with the follow-up work that finance teams need. That is a meaningful direction because card issuance without expense discipline can simply move the mess from cash reimbursements to card statements.
I would not read the current version as a promise that every company will receive the same experience. Business software changes according to account roles, approval structures, and administrative choices. For that reason, existing users should evaluate an update by asking whether it makes their daily tasks clearer: finding a transaction, adding context, checking an approval status, or resolving an incomplete expense.
The strongest sign of useful evolution is not a new visual detail; it is less friction between an employee’s purchase and the finance team’s ability to understand it. If an update reduces duplicate entry or makes an overlooked expense easier to identify, it has real value. If it merely moves familiar controls around, users may need a short adjustment period without receiving a meaningful workflow improvement.
What existing users should expect
People already using the service should think of the mobile app as one part of a shared operating routine. An employee’s habits affect the quality of the finance team’s records, and a manager’s review habits affect whether the system feels fast or bureaucratic. The app can support both sides, but it cannot compensate for unclear ownership.
My practical advice is to agree on a simple internal sequence before asking everyone to use it: record the purchase promptly, add the business context while it is fresh, attach the supporting material your policy requires, and respond quickly when something is returned for clarification. This is not a hidden button or a special feature; it is the workflow insight that makes the mobile format worthwhile.
Existing users should also be careful during any interface change. A familiar path may move, and employees who only use the app once or twice a month are the most likely to miss a new prompt. A short internal guide with screenshots from the current setup can be more helpful than a long policy document. Finance administrators should test the process with an ordinary employee account, not only an administrator view, because the two experiences can feel very different.
Where the app may still frustrate people
The first limitation is that this is business software, not a casual utility. Someone expecting to open it and immediately understand every option may find the experience more demanding than a personal banking app. The terminology, roles, and approval logic are connected to company administration, so the smoothness of the experience depends partly on decisions made outside the phone.
The second limitation is the risk of overkill for a tiny operation. If a business has very few expenses, one trusted cardholder, and no meaningful approval chain, introducing a structured expense platform may create more process than it removes. In that situation, a direct accounting workflow or a simple shared record could be easier to maintain.
There is also a human limitation: mobile capture is only useful if people do it at the right time. A receipt can still be lost, a description can still be vague, and a manager can still delay a review. The app improves the path, but it does not guarantee disciplined behavior. Companies should avoid assuming that installation equals adoption.
Another trade-off concerns dependence on the organization’s broader setup. The app’s usefulness is tied to how corporate cards, employee roles, and expense policies are arranged. A person looking for a standalone tool to manage unrelated personal purchases should choose something designed for that purpose instead. This product makes more sense when the employer has already built a business spending process around it.
Who should use it and who should skip it
I would recommend it to a growing company that wants employees to document spending close to the time it happens. It is especially relevant for teams with people traveling, working remotely, purchasing supplies, or charging expenses to different projects. The mobile format can help those employees avoid carrying a backlog of receipts into the end of the month.
It may also suit finance teams that are tired of reconciling card statements with separate email threads. Bringing the employee’s explanation closer to the transaction can make follow-up more focused. The benefit is greatest when managers are willing to use the same process consistently rather than approving some purchases by email and others inside the app.
I would skip it for personal budgeting, informal household expense sharing, or a business that has no need for corporate card oversight. I would also compare it carefully with a full accounting suite if your main requirement is advanced bookkeeping, tax preparation, inventory, or detailed financial reporting. BILL Spend & Expense addresses spending control and expense handling; it should not be treated as a replacement for every financial system a company may need.
Questions to settle before adoption
One practical question is whether employees need a company account or organization invitation rather than simply downloading the app. Since this is designed around business spending, the answer depends on how the employer has configured access. Before rolling it out, an administrator should confirm who can use the mobile workflow and what each role is expected to do.
Another question is whether it will replace existing accounting work. I would not assume that it does. The sensible evaluation is to map one complete expense from purchase through review and whatever finance process follows. If information still has to be copied manually into another system, the app may remain useful, but its real time-saving benefit will be smaller than expected.
Users may also wonder whether a phone is enough for every task. For quick actions around a purchase, mobile access is the main advantage. For administrative setup, policy design, and reviewing a large volume of expenses, a larger screen and a dedicated finance workflow may be more comfortable. I see the app as strongest at the point of spending and review, not necessarily as the only interface for every business task.
Finally, companies should ask how they will measure adoption. Counting installations is not enough. A better test is whether employees submit clearer records sooner and whether managers spend less time asking what a transaction was for. That kind of before-and-after comparison will reveal more than the app’s rating alone.
What I would watch next
Because the product already combines corporate cards with expense management, I would watch for improvements that make the handoff between those two areas more transparent. Users should be able to understand what needs attention without hunting through several screens. Clear status information, sensible reminders, and fewer duplicate steps would matter more to me than cosmetic redesign.
I would also watch how the app handles the needs of different roles. An employee wants speed, a manager wants enough context to make a decision, and finance staff want dependable records. The best future changes will balance those needs instead of making one group’s work easier by shifting effort to another.
For existing customers, the most useful updates will be the ones that preserve familiar routines while removing small points of friction. For new customers, the key question is whether the current version fits the company’s policy without requiring employees to become finance specialists. Those are expectations rather than guarantees, so I would test the complete workflow before committing a whole team.
My final assessment
BILL Spend & Expense is a focused business app that makes the most sense when corporate card activity and expense follow-up need to live in the same organized process. I like its practical purpose and its mobile-first timing: the closer documentation happens to the purchase, the less likely the business is to depend on memory and scattered receipts.
It is not the right answer for every financial task, and smaller teams may find a simpler method more efficient. Its success also depends heavily on company setup and employee habits. Still, for organizations that need clearer spending visibility, a shared approval routine, and a more dependable way to collect expense context, I think it is worth considering.
Bill.com Inc. has kept the product active through a long period of development, and the current 4.0.17 release presents it as a mature option rather than a bare card companion. With a free price and an Everyone rating, it is easy to try within an eligible business environment. My recommendation is to pilot it with one real spending workflow first. If it reduces late receipts and repeated clarification messages, it is doing exactly the job this category of app should do.
FAQ
What is BILL Spend & Expense (Divvy), and who is it designed for?
BILL Spend & Expense, formerly known as Divvy, is a business spending and expense management platform designed for companies, finance teams, and employees who need better control over corporate purchases. It combines expense tracking, budgets, approvals, corporate cards, receipt collection, and reporting in one system. It is generally more useful for organizations than for individuals managing personal finances.
Can employees use the app to submit expenses and receipts?
Yes. Employees can typically use the mobile app to record business expenses, upload or photograph receipts, add notes, and submit transactions for review. Depending on the company’s configuration, the app may also connect card purchases with receipts automatically and send reminders for missing information. Available features can vary according to the employer’s BILL subscription, policies, permissions, and account setup.
Does BILL Spend & Expense include corporate cards and spending limits?
The platform can support company-issued spending cards and configurable spending controls, allowing organizations to establish budgets, limits, approval rules, and merchant restrictions. These tools are intended to help finance managers monitor spending before and after a purchase occurs. However, card availability, transaction permissions, reimbursement options, and specific controls depend on the employer’s plan and administrative configuration.
Is BILL Spend & Expense secure for handling business and financial information?
BILL Spend & Expense is built for business financial workflows and uses account authentication, permission controls, and protected connections to help safeguard company data. Even so, users should keep the app updated, use a strong unique password, protect their device, and avoid sharing login details. Security features and login options may differ depending on the organization’s account policies and supported devices.
Is BILL Spend & Expense free to download and use?
The mobile application may be available to download without an upfront charge, but access to its business features is normally connected to a company account, paid subscription, or employer invitation. Individual users may not be able to create a fully functional account independently. Before downloading, employees should confirm that their organization uses BILL Spend & Expense and check whether their administrator has enabled mobile access.


